Augusta Gold IRA Storage Options: Depository, Fees, and Rules
TL;DR: Augusta Precious Metals cannot ship gold IRA bullion to a customer's house. IRC 408(m)(3) requires a qualified trustee to hold the metal, and the Tax Court's 2021 McNulty ruling confirmed that home possession triggers a taxable distribution. Augusta's primary storage partner is the Delaware Depository in Wilmington, Delaware, with vault contents insured under Lloyd's of London. The default arrangement is commingled storage for a $100 annual fee, and segregated storage is available as a paid upgrade. This guide covers who holds the metal, where it sits, what the fee buys, and which coins and bars actually qualify.
Augusta Precious Metals gold IRA storage runs through a three-party structure that keeps the account tax-advantaged. Augusta sells the metal, an approved custodian administers the retirement account, and a separate depository physically vaults the coins and bars under the account holder's name. That structure exists because federal law bars an IRA owner from taking personal possession of gold IRA metal while the account keeps its tax status, a rule the U.S. Tax Court reinforced in 2021 when it ruled against a saver who kept coins in a home safe. Money magazine named Augusta Precious Metals its Best Overall Gold IRA Company for four consecutive years from 2022 through 2025, and Augusta's gold IRA process folds storage questions into the same onboarding call that covers account setup and metal selection. What follows walks through each piece of that structure, the legal reason home storage is off the table, the roles each party plays, where Augusta actually stores metal, how commingled and segregated storage differ, what the storage fee pays for, and which coins and bars clear the eligibility bar before they ever reach a vault.
The short answer is federal tax law. IRC 408(m)(3) allows an individual retirement account to hold gold, silver, platinum, and palladium bullion only when a qualified trustee keeps physical possession of it. An account holder who takes the metal home is treated as receiving a taxable distribution, not as safeguarding a personal asset.
That distinction sounds technical, but the dollar consequences are not. In McNulty v. Commissioner, decided by the Tax Court on November 18, 2021, an IRA owner had American Eagle coins shipped to a safe she kept at home through an IRA-owned LLC. The court held that arrangement counted as a distribution the moment she took the coins, and the case ended with back taxes and penalties above $300,000. Augusta Precious Metals structures every account so a saver never has to make that mistake, because the metal Augusta sells routes directly to an IRS-approved depository instead of a home address.
Why does one saver's case matter this much? It is the clearest signal the courts have given that a self-directed IRA owner cannot act as her own trustee, no matter how the account is technically structured. The home storage myth has circulated in gold IRA marketing for years, usually pitched as a loophole through an LLC the IRA owns. McNulty closed that loophole. Physical possession has to sit with a trustee, and an LLC manager taking the coins home does not meet that bar under
IRC 408(m)(3).
A saver who buys IRA-eligible bullion still gets full ownership rights on paper. Account statements list the exact bars and coins in a person's name, and the metal cannot be sold, moved, or melted without that person's consent. What changes is custody, not ownership. The coins sit in a vault instead of a drawer, and that single difference keeps the account's tax advantages intact through years of contributions and eventual distributions.
Home-storage gold IRA promotions still surface in search results and social media ads years after McNulty, often marketed as a checkbook-IRA workaround that predates the ruling. Augusta's compliance posture rules that structure out entirely by shipping every ounce of IRA-purchased metal straight to a depository, with no home-storage LLC option offered at any point in the sales process.
Three separate companies touch an Augusta gold IRA before any metal reaches a vault. Augusta Precious Metals is the dealer that sells the coins and bars. A separate custodian administers the retirement account and files the required tax paperwork. A third company, the depository, physically stores the metal.
On most Augusta accounts the administering custodian is Equity Trust Company, and GoldStar Trust Company and Kingdom Trust stand available for savers who prefer a different provider, per Augusta Precious Metals. Augusta points to Equity Trust as its top recommendation while leaving the final choice to the account holder. The custodian's job has nothing to do with picking metal or setting prices. It opens the self-directed account, accepts the transferred funds, and issues the tax forms a saver needs every spring, Form 5498 for contributions and rollovers and Form 1099-R for any distribution.
Why split the work across three companies instead of one? The separation is a regulatory feature, not a marketing quirk. Treasury regulations at 26 CFR 1.408-2 require a nonbank trustee to demonstrate fiduciary capacity, adequate net worth, and formal auditing protocols before the IRS approves it to hold retirement assets. That approval process is what lets a custodian like Equity Trust Company administer precious-metals IRAs at all, separate from any license or reputation Augusta carries as a metals dealer.
A dedicated Augusta agent stays involved through every stage of the transfer even though Augusta itself never touches the physical vault. Some customers assume Augusta stores the metal directly, and a recurring theme in customer reviews is surprise at meeting a second company's name on custodian statements after the account opens. That second name is expected, not a red flag. It confirms the account is following the same third-party structure every compliant precious-metals IRA has to use.
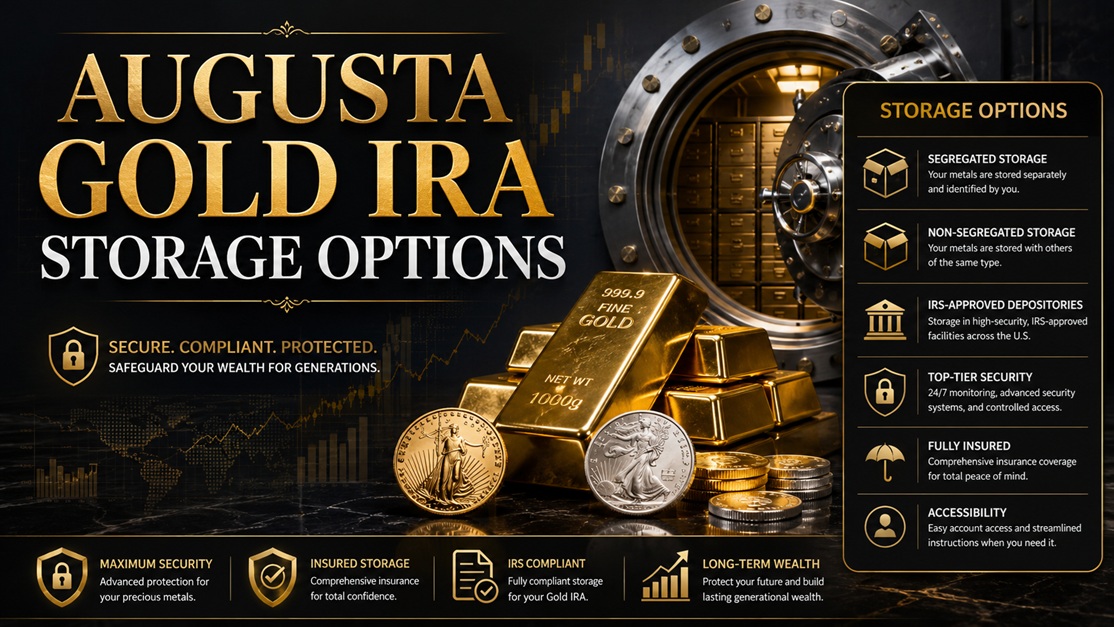
Augusta's primary storage partner is the Delaware Depository in Wilmington, Delaware, an IRS-approved facility that insures vault contents under Lloyd's of London. Additional storage relationships extend to Brink's Global Services and Texas Precious Metals Depository, giving Augusta more than one approved location to route a customer's purchase.
The Delaware Depository handles the bulk of Augusta's storage volume, and its Lloyd's of London insurance coverage is the detail account holders ask about most once they understand the custody structure. Every bar and coin ships directly from Augusta's supplier network to the depository, never through the customer's hands, which keeps the chain of custody intact for IRS purposes.
Does a saver get to pick which depository holds the metal? Augusta assigns a primary facility based on account type and metal selection, and the dedicated agent walks through where a specific purchase will land before the transfer completes. Brink's Global Services operates depository locations in multiple states, and Texas Precious Metals Depository adds a Texas-based option some savers prefer for state-specific reasons. None of these facilities compete with Augusta. Each one is a storage partner, not a company account holders deal with directly on pricing or account service.
Once metal arrives, the depository issues its own confirmation separate from the custodian's paperwork, and both records list the exact holding under the account holder's name and account number. A saver never receives a physical delivery notice the way a retail purchase would generate one, because the shipment never passes through a personal address at any point in the process. That absence of a delivery step is by design, not an oversight, and it is the same design McNulty confirmed the law actually requires.
Augusta's default gold IRA storage is commingled, not segregated. Commingled storage means a customer's bars and coins sit in the same vault space as other customers' matching products, tracked by account ownership rather than by a physically separated bin. Augusta's published fee schedule lists a $100 annual charge specifically for non-segregated storage, confirming commingled is the standard arrangement rather than an exception.
What is the practical difference between the two? Segregated storage, sometimes called allocated storage, keeps a specific customer's exact bars and coins physically apart from every other account's holdings inside the same depository. Commingled storage instead tracks ownership through custodian and depository records while like-for-like product sits together in shared vault space, similar to how a brokerage tracks shares of the same stock without assigning each customer a specific physical certificate.
Segregated storage is available through Augusta as a paid upgrade for savers who want that added separation, though the exact upgrade cost depends on account size and metal mix, and a dedicated agent quotes that figure directly rather than publishing it as a flat rate. The commingled default is not a downgrade in security. Both storage types sit inside the same IRS-approved, insured depository, and both are tracked to the account holder's name on every statement.
Cost efficiency drives the commingled default across the gold IRA industry generally, since segregated storage requires the depository to allocate dedicated space rather than pooling like products together. A saver who wants the segregated option simply asks for it during account setup, and the fee structure adjusts from the standard $100 annual non-segregated rate to whatever the segregated arrangement costs for that specific account.
Augusta's storage fee pays the depository directly for vault space, insurance coverage, and the recordkeeping that ties inventory to a specific account. The published rate is $100 per year for non-segregated storage, part of a broader fee stack that totals $275 in the first year and $225 in every year after.
That first-year total breaks into three separate charges. A $50 one-time setup fee opens the self-directed account, a $125 annual custodian fee pays Equity Trust Company or the chosen alternate for account administration, and the $100 storage fee covers the depository relationship described above. None of the three fees goes to Augusta directly, since Augusta's compensation on a transaction comes from the spread between what it pays for metal and what it charges the customer, not from the ongoing account fees.
How does a saver know the metal is actually there? The custodian sends account statements listing the exact holding, and the depository backs that listing with its own inventory confirmation. Form 5498 arrives each spring reporting that year's contributions and rollover activity, and Form 1099-R only comes into play if the account takes a distribution, whether in cash or as an in-kind metal shipment. Reading both forms alongside the custodian statement is the simplest way to confirm nothing has changed in an account's holdings from one year to the next.
Full detail on how Augusta prices the rest of the account, including the metal spread quoted during the enrollment call, lives in the Augusta Precious Metals pricing breakdown elsewhere on this site. Storage is only one line on that broader fee schedule, and it is worth reading alongside the custodian and setup charges rather than in isolation.
Only metal that clears a specific purity threshold ever reaches an Augusta depository, because the custodian will not accept a shipment that fails to meet the standard. Gold has to reach at least 99.5 percent fineness and silver at least 99.9 percent, or the product has to be one of a short list of statutorily named coins, before Augusta ships it for storage.
That standard comes directly from the same statute that permits the account structure in the first place. IRC 408(m)(3) ties eligibility to the fineness a regulated futures exchange requires for delivery, which is why the threshold tracks industry benchmarks rather than a number Augusta sets on its own. Coins like the American Gold Eagle qualify through a separate statutory carve-out rather than the fineness test, since the Eagle's actual gold content would otherwise fall short of the 99.5 percent line.
What happens to metal that does not qualify? It never becomes part of the IRA in the first place. Augusta's product catalog for retirement accounts is restricted to bullion and coins that already clear the eligibility bar, so a saver shopping inside the IRA program is not choosing between eligible and ineligible products. Numismatic and collectible coins marketed outside that eligible list belong in a personal collection, not a tax-advantaged retirement account, and buying one inside an IRA risks the same prohibited transaction exposure covered elsewhere on this site.
Why does the depository double-check fineness before accepting a shipment? Because the depository's own IRS approval depends on only holding eligible retirement-account assets, so it has its own incentive to reject anything that would put that approval at risk. The result is a second layer of verification beyond Augusta's own sourcing standards, giving a saver two separate checks confirming the metal in the account actually qualifies for the tax treatment the account depends on.
Augusta requires a $50,000 minimum to open a precious-metals IRA, and that figure shapes how much metal actually needs vault space from day one. A saver funding the minimum account is typically shipping a meaningful quantity of gold or silver in a single initial purchase rather than building the position gradually.
Consumer Affairs lists Augusta's $50,000 minimum as the highest among major gold IRA providers, a threshold that filters the account toward savers rolling over an existing 401(k) or IRA balance rather than starting from a small initial contribution. That scale matters for storage because a first purchase at or above the minimum typically fills a meaningful fraction of a standard vault allocation immediately, rather than accumulating gradually over several years of smaller purchases.
Does a larger initial purchase change which depository handles the account? Not directly. Account size affects which storage tier a saver might consider, since segregated storage becomes more appealing as the dollar value of a holding grows, but the underlying depository relationship, whether Delaware Depository, Brink's Global Services, or Texas Precious Metals Depository, stays the same regardless of account size. The rollover process that gets a saver to the $50,000 threshold is worth understanding on its own, since most savers reach it by moving an existing retirement balance rather than contributing new cash.
A saver approaching the minimum should treat the storage decision as part of the same conversation as the funding decision, not a separate step handled later. The dedicated agent who walks through account minimums during onboarding is the same person who explains commingled versus segregated storage, so both decisions typically happen on the same call before any metal purchase clears.
Frequently Asked Questions
Does Augusta Precious Metals Offer Home Storage for Gold IRAs?
No. Augusta ships every IRA-eligible purchase directly to an IRS-approved depository, never to a customer's home address. IRC 408(m)(3) requires a qualified trustee to hold gold IRA metal, and the Tax Court's 2021 ruling in McNulty v. Commissioner confirmed that personal possession, even through an IRA-owned LLC, counts as a taxable distribution. A saver who wants to hold physical gold at home can still do so outside a retirement account, but that purchase loses the tax-advantaged treatment an IRA provides and has to be funded with after-tax dollars instead.
Is Augusta Gold IRA Storage Segregated or Commingled by Default?
Commingled. Augusta's published $100 annual fee applies to non-segregated storage, confirming that shared vault space is the standard arrangement rather than a discount option. Segregated storage, which keeps a customer's exact bars and coins physically apart from other holdings, is available as a paid upgrade for savers who want that extra separation. Both storage types sit inside the same insured, IRS-approved depository and both are tracked to the account holder's name on every statement, so the distinction affects vault placement rather than security or ownership.
Where Does Augusta Store Gold and Silver IRA Metal?
Augusta's primary storage partner is the Delaware Depository in Wilmington, Delaware, with vault contents insured under Lloyd's of London. Additional storage relationships extend to Brink's Global Services and Texas Precious Metals Depository, giving Augusta more than one IRS-approved facility to route a customer's purchase. A dedicated agent confirms which depository will hold a specific purchase before the transfer completes, and the custodian's account statements list the resulting holding under the account holder's name and account number once metal arrives.
What Metal Purity Does Augusta Require for IRA Storage?
Gold has to reach at least 99.5 percent fineness and silver at least 99.9 percent before Augusta ships it to a depository, unless the product is one of a short list of statutorily named coins such as the American Gold Eagle. That threshold comes from IRC 408(m)(3), which ties eligibility to the fineness a regulated futures exchange requires for delivery. Numismatic and collectible coins marketed outside that eligible list do not qualify for IRA storage regardless of their gold or silver content.
Risk Warning: Precious metals investments carry risk, including the possible loss of principal. Gold and silver prices can fluctuate based on macroeconomic conditions, currency movements, and market sentiment. Past performance is not a guarantee of future results. Storage arrangements, custodian relationships, and depository partners can change over time, so confirm current details directly with Augusta before opening or funding an account. IRS rules governing self-directed retirement accounts and storage requirements are complex and subject to change. Always consult your own licensed legal, financial, and tax professionals before opening or funding a gold IRA.
About the Editorial Team
Augusta Precious Metals Reviews is the editorial site covering Augusta Precious Metals. We publish articles about Augusta's products, leadership, fees, customer experience, and gold IRA process under an editorial team byline. Our coverage cites named third-party authorities, including the Internal Revenue Service and Money magazine, alongside Augusta's own published positioning. We do not publish urgent, scarcity-driven, or high-pressure content. We close every educational article with a soft reminder to speak with your own legal, financial, and tax professionals before investing.
Disclosure: This site has a partnership relationship with Augusta Precious Metals and may earn a commission from accounts opened through the contact methods on this site, in line with the Federal Trade Commission affiliate-disclosure rules under 16 CFR Part 255. Editorial coverage reflects Augusta's published positioning and the current rules governing self-directed precious-metals IRAs.
Disclaimer: This article is for informational purposes only and does not constitute financial, tax, or legal advice. Consult a qualified professional before making investment decisions.