Augusta Precious Metals and the Delaware Depository: A Storage FAQ
TL;DR: Augusta Precious Metals ships IRA gold and silver to the Delaware Depository in Wilmington, Delaware, an IRS-approved vault that insures its holdings under Lloyd's of London. Federal law is the reason the metal goes there instead of a customer's house. Under IRC 408(m)(3) the bullion has to stay in a qualified trustee's hands, and in McNulty v. Commissioner the Tax Court ruled in 2021 that a saver who kept coins in a home safe had taken a taxable distribution. A custodian, typically Equity Trust Company, administers the account and sends the yearly tax forms, while the depository handles physical custody of the metal itself. Augusta also references Brink's Global Services and the Texas Precious Metals Depository as additional storage options.
Every Augusta Precious Metals gold IRA answers the same underlying question differently than a typical purchase would. Bullion bought for an IRA never reaches the buyer's hands. It ships instead to the Delaware Depository, an IRS-approved vault in Wilmington, Delaware that insures its contents under Lloyd's of London. That routing isn't a policy choice Augusta made on its own. Federal tax law requires it, and a Tax Court ruling from 2021 made the consequence of ignoring that requirement extremely expensive for at least one saver. This page walks through what the Delaware Depository actually is, why the law forces metal there instead of a home safe, how a custodian's job differs from a depository's job, which other storage partners Augusta references, and how an account holder confirms the metal is actually sitting where the paperwork says it is.
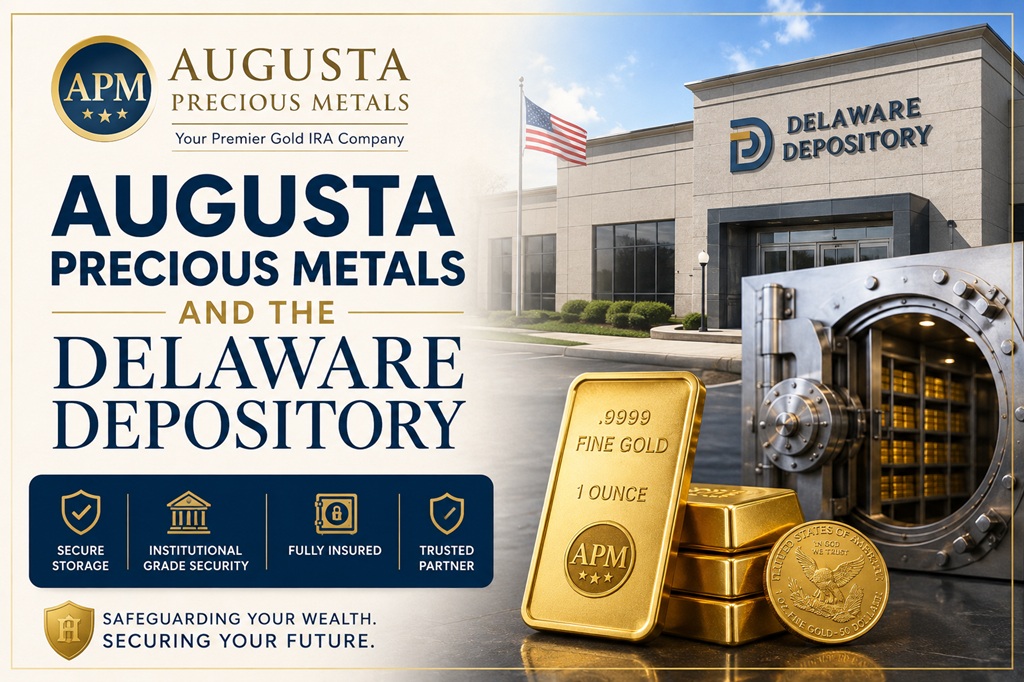
The Delaware Depository is Augusta's primary storage partner for IRA-purchased gold and silver, an IRS-approved facility located in Wilmington, Delaware. Vault contents at the facility carry insurance coverage placed through Lloyd's of London, a detail that comes up often once a saver understands why the metal can't just sit at home.
Augusta itself runs its operations from a Beverly Hills, California base, a separate matter entirely from where the actual bullion sits once an account holder buys it. That distinction trips up more than a few first-time savers. One address is where Augusta's staff works, answers calls, and processes paperwork. The other is where the metal itself lives, insured and inventoried under the account holder's name, hundreds of miles away in a facility Augusta doesn't own or operate.
Why funnel every purchase to one primary facility rather than scattering it across several? Concentrating volume at a single IRS-approved depository keeps the chain of custody simple to document, and it gives Augusta's dedicated agents a consistent answer when a saver asks where a specific purchase will land. A saver who buys through Augusta doesn't choose a depository the way someone picks a bank branch. The dedicated agent assigned during account setup confirms the destination before the transfer completes, and the arrangement rarely varies from the Delaware facility for a standard purchase.
A saver comparing Augusta to a generic retail bullion purchase sometimes expects a shipping tracking number the way an online order would generate one. That expectation doesn't quite fit here. The depository issues its own confirmation once the shipment clears, separate from anything a retail carrier would generate, because the metal never passes through a residential delivery address at any point in the transaction.
Home storage fails for one reason: the tax code requires a qualified trustee to physically hold gold IRA bullion, not the account owner. IRC 408(m)(3) permits an IRA to hold gold, silver, platinum, and palladium only when that trustee keeps physical possession, and an account holder who takes the coins home is treated as receiving a taxable distribution rather than safeguarding a personal asset.
That rule stopped being theoretical in 2021. In McNulty v. Commissioner, the Tax Court ruled against a saver who had American Eagle coins shipped to a home safe through an IRA-owned LLC. Judges treated that arrangement as a distribution the moment she took possession. Back taxes and penalties on the case closed above $300,000. Augusta structures every account so a saver never faces that outcome, since the metal it sells routes straight to a depository rather than a home address.
Does an LLC wrapper change the outcome? McNulty answered that question directly, and the answer was no. The home storage gold IRA myth has circulated in marketing pitches for years, usually framed as a loophole an account owner's own LLC could exploit. That loophole closed for good with the ruling. Physical possession has to sit with a trustee, full stop, and a self-directed IRA owner acting as her own custodian doesn't satisfy that bar no matter how the paperwork is structured.
Two separate companies handle an Augusta gold IRA before any bullion reaches a vault, and neither one is Augusta itself. A custodian administers the retirement account and files the required tax paperwork, while a depository physically stores the coins and bars under lock and inventory.
Equity Trust Company serves as the custodian Augusta recommends most often, though GoldStar Trust Company and Kingdom Trust operate as approved alternatives for savers who prefer a different provider. Not one of the three touches the metal directly. Their job starts and ends with opening the self-directed account, accepting transferred funds, and issuing Form 5498 each year for contributions and rollovers, plus Form 1099-R whenever a distribution occurs. The Delaware Depository, by contrast, never opens an account or sends a tax form, since it simply holds the physical metal and confirms its location.
Treasury regulations spell out exactly why this division of labor exists. 26 CFR 1.408-2 requires a nonbank trustee to demonstrate fiduciary capacity, adequate net worth, and formal auditing protocols before the IRS approves it to hold retirement assets, an approval process entirely separate from anything Augusta carries as a metals dealer. A saver who expects one company to handle both the account and the vault sometimes finds the second name on a custodian statement surprising. It shouldn't be. Seeing a custodian's name alongside a depository's name is exactly what a compliant, third-party-verified structure looks like.
Three names end up on the paperwork trail for a single purchase, and each one plays a distinct role a saver benefits from keeping straight. Augusta sells the metal and coordinates the transfer. A custodian administers the account and answers to the IRS for how it's run. Physical custody, meanwhile, belongs to the depository, which holds the bars and coins and answers for their safekeeping. Not one of the three substitutes for another, and a saver who tries to shortcut the structure by treating any single name as the whole picture usually ends up confused the first time a statement arrives from a company they don't remember signing up with directly.
Delaware isn't the only facility Augusta references, though it remains the principal storage partner for most purchases. Augusta also names Brink's Global Services and the Texas Precious Metals Depository as additional storage options available for certain accounts.
Neither alternate facility competes with Augusta on price or service. Both are storage partners in the same sense the Delaware Depository is, meaning they hold metal and confirm inventory rather than sell it or manage the retirement account. A saver rarely chooses between the three the way someone compares dealers, since the dedicated agent handling a specific purchase confirms which facility applies before the transfer clears.
What determines which vault gets used for a given purchase? Account type and metal selection typically decide it, and Augusta's default routing sends the bulk of its volume to Delaware. A saver curious about a different location can raise the question directly with the assigned agent, though switching facilities mid-purchase isn't something most accounts require or request.
Nothing here changes the underlying legal structure a saver already agreed to when opening the account. It makes no difference whether the metal lands in Wilmington, at a Brink's-operated facility, or at the Texas location. The same custodian keeps the paperwork, the same IRS eligibility rules apply to the bullion itself, and the same prohibition on personal possession governs every one of these approved sites equally. A saver picking between depositories is choosing a warehouse, not a different set of rules.
An account holder confirms holdings through paperwork, not a personal visit to the vault. The custodian sends account statements listing the exact bars and coins under the saver's name, and Form 5498 arrives every spring documenting that year's contributions and rollovers.
Form 1099-R only enters the picture if the account takes a distribution, whether as cash or as an in-kind metal shipment. Checking the custodian statement alongside whichever of those two forms applies is the simplest way an account holder confirms nothing unexpected changed in the account from one year to the next. The Augusta gold IRA process folds this reporting rhythm into the same onboarding conversation that covers account setup and metal selection, so a new saver isn't left guessing when the first statement should arrive.
How does this compare with a typical retail purchase? A broad survey of the gold IRA industry shows minimums and fee stacks that vary widely across providers, but the underlying custodian-and-depository reporting structure Augusta uses is standard across compliant self-directed IRAs, not something unique to one company. Savers who grasp that structure early rarely find the paperwork confusing later.
Frequently Asked Questions
Is Augusta Precious Metals the Same Company as the Delaware Depository?
No. The Delaware Depository is an independent, IRS-approved storage facility in Wilmington, Delaware, not a division of Augusta Precious Metals. Augusta sells the metal and connects a saver with a custodian, but a separate depository physically holds the bullion once it ships. Vault contents carry insurance placed under Lloyd's of London, and the depository issues its own inventory confirmation apart from anything Augusta or the custodian sends.
What Happens if an Augusta IRA Holder Tries to Store Gold at Home?
Personal possession of gold IRA metal, even through an IRA-owned LLC, counts as a taxable distribution under IRC 408(m)(3). The Tax Court's 2021 ruling in McNulty v. Commissioner confirmed that outcome, and the case ended with back taxes and penalties above $300,000 for the saver involved. Augusta avoids this exposure entirely by shipping every IRA purchase directly to an approved depository rather than a home address.
Does Delaware Depository Insurance Cover Stored Metal?
Vault contents at the Delaware Depository carry insurance placed under Lloyd's of London, covering the bullion held on behalf of Augusta account holders. Exact policy terms and coverage details can change, so a saver who wants the current specifics should confirm them directly with Augusta before funding an account rather than relying on a general description.
Which Company Sends the Tax Forms for an Augusta Gold IRA?
The custodian, typically Equity Trust Company or one of its approved alternates, sends the tax paperwork, not the depository. Form 5498 reports each year's contributions and rollovers, and Form 1099-R applies only if the account takes a distribution. The Delaware Depository never issues either form, since its role starts and ends with physical custody of the metal.
Risk Warning: Precious metals investments carry risk, including the possible loss of principal. Gold and silver prices can fluctuate based on macroeconomic conditions, currency movements, and market sentiment. Past performance is not a guarantee of future results. Storage arrangements, custodian relationships, and depository partners can change over time, so confirm current details directly with Augusta before opening or funding an account. IRS rules governing self-directed retirement accounts are complex and subject to change. Always consult your own licensed legal, financial, and tax professionals before opening or funding a gold IRA.
About the Editorial Team
Augusta Precious Metals Reviews is the editorial site covering Augusta Precious Metals. We publish articles about Augusta's products, leadership, fees, customer experience, and gold IRA process under an editorial team byline. Our coverage cites named third-party authorities, including the U.S. Tax Court and Consumer Affairs, alongside Augusta's own published positioning. We do not publish urgent, scarcity-driven, or high-pressure content. We close every educational article with a soft reminder to speak with your own legal, financial, and tax professionals before investing.
Disclosure: This site has a partnership relationship with Augusta Precious Metals and may earn a commission from accounts opened through the contact methods on this site, in line with the Federal Trade Commission affiliate-disclosure rules under 16 CFR Part 255. Editorial coverage reflects Augusta's published positioning and the current rules governing self-directed precious-metals IRAs.
Disclaimer: This article is for informational purposes only and does not constitute financial, tax, or legal advice. Consult a qualified professional before making investment decisions.